CHIN UCITS ETF: China ETF | S&P China 500 | KraneShares
by Kraneshares
30/Sep/2026 info@kraneshares.com This is a marketing communication. Please refer to the prospectus of the UCITS, the KIID, and the PRIIP before making any final investment decisions. The tax treatment depends on the individual circumstances of each client and may be subject to change in the future. Diversification Opportunities From Capturing China as an Asset Class An Overview of the KraneShares ICBCUBS S&P China 500 Index UCITS ETF (Ticker: CHIN) CHIN
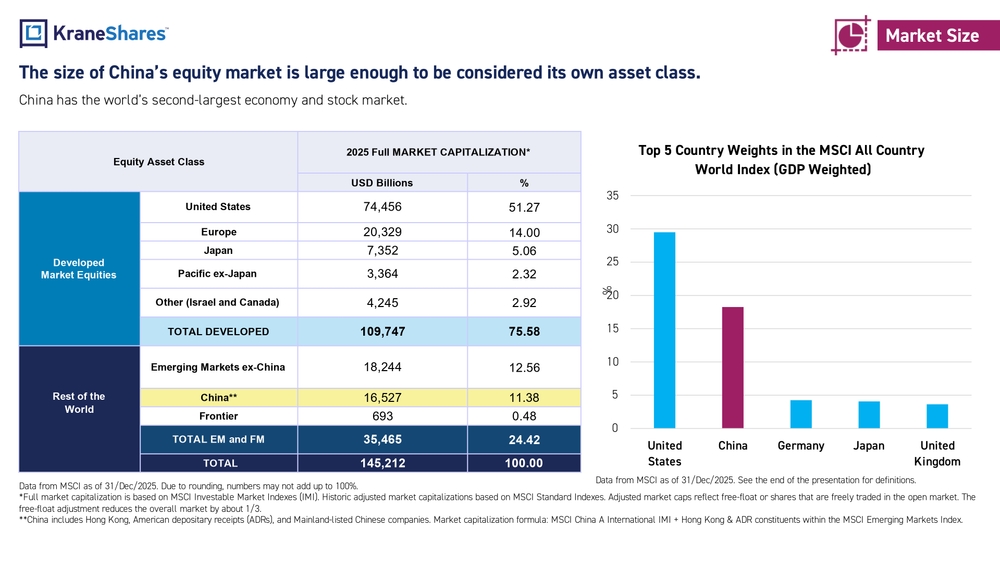
2 Investment Strategy: CHIN is a passively managed, index-tracking UCITS ETF that seeks to track the S&P China 500 Index. The S&P China 500 Index comprises 500 of the largest, most liquid Chinese companies listed on all Chinese stock exchanges, including Mainland China, Hong Kong, and the United States. Companies available for inclusion must be headquartered in China and meet the market capitalization and liquidity minimums required by S&P’s index methodology. CHIN Features: • Strategic ownership of China as an asset class. • Exposure to companies benefitting from increasing domestic consumption by China's growing middle class. • Exposure to Chinese companies listed in the United States, Hong Kong, and Mainland China. China Broad Equity Market Highlights: • The increased availability of Chinese equities to foreign investors over the past decade has brought about the rise of China as an asset class. • China has the world’s second largest economy and equity market, with a capitalization of over $16 trillion.1 CHIN KraneShares ICBCUBS S&P China 500 Index UCITS ETF
- Data from MSCI as of 12/31/2025. The Fund’s assets are expected to be concentrated in a sector, industry, market, or group of concentrations to the extent that the Underlying Index has such concentrations. The securities or futures in that concentration could react similarly to market developments. Thus, the Fund is subject to loss due to adverse occurrences that affect that concentration.
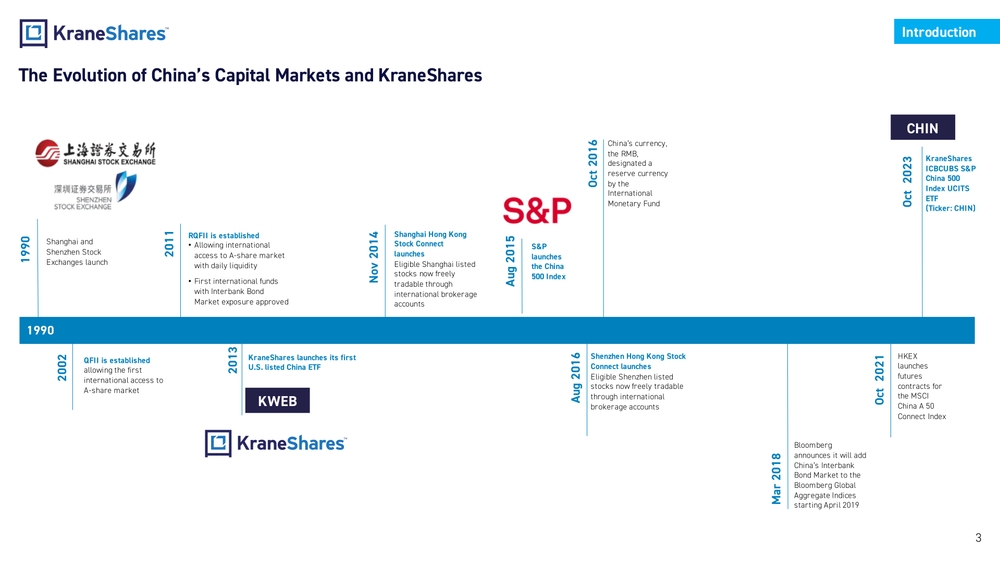
3 The Evolution of China’s Capital Markets and KraneShares 1990 Shanghai and Shenzhen Stock Exchanges launch Shenzhen Hong Kong Stock Connect launches Eligible Shenzhen listed stocks now freely tradable through international brokerage accounts Aug 2016 QFII is established allowing the first international access to A-share market 2002 RQFII is established • Allowing international access to A-share market with daily liquidity • First international funds with Interbank Bond Market exposure approved 2011 1990 Shanghai Hong Kong Stock Connect launches Eligible Shanghai listed stocks now freely tradable through international brokerage accounts Nov 2014 KraneShares launches its first U.S. listed China ETF 2013 Oct 2016 China’s currency, the RMB, designated a reserve currency by the International Monetary Fund Mar 2018 Bloomberg announces it will add China’s Interbank Bond Market to the Bloomberg Global Aggregate Indices starting April 2019 HKEX launches futures contracts for the MSCI China A 50 Connect Index Oct 2021 Introduction KraneShares ICBCUBS S&P China 500 Index UCITS ETF (Ticker: CHIN) Oct 2023 CHIN KWEB S&P launches the China 500 Index Aug 2015
The Index Matters S&P is a world-leading resource for benchmarks and investable indices. Data from S&P Dow Jones as of 30/Sep/2026. For illustrative purposes only. Indexes are unmanaged and one cannot invest directly in an index. 4 Index Overview Global Reach Clients in 71 Countries & 21 offices worldwide Index Services (Index Licensing, Custom Indices, and Data and Benchmarking)
What is the S&P China 500 Index? The S&P China 500 Index comprises 500 of the largest, most liquid Chinese companies while approximating the sector composition of the broader Chinese equity market. Potential benefits of the S&P China 500 Index: • Industry representation and diversification* • Targets the complete opportunity set • Passive investment approach • Access to leading companies and A-Share exposure S&P Dow Jones Indices helps investors around the globe make decisions with conviction As the world’s leading resource for benchmarks and investable indices, their solutions are widely considered indispensable in tracking market performance, evaluating portfolios, and developing investment strategies. 5 *Diversification does not guarantee a profit or ensure against a loss. S&P Dow Jones as of 30/Sep/2026. Index Overview
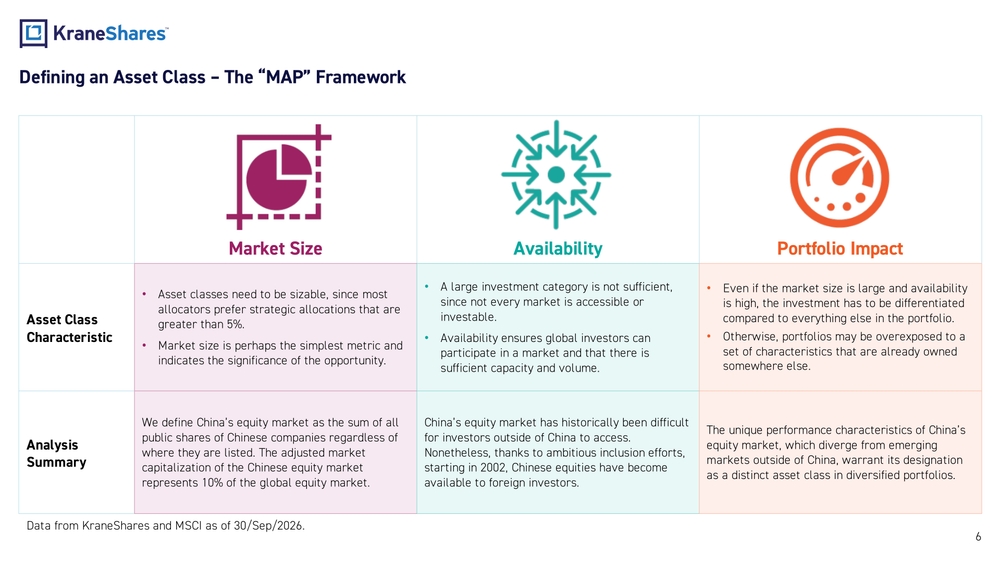
Defining an Asset Class – The “MAP” Framework Market Size Availability Portfolio Impact Asset Class Characteristic • Asset classes need to be sizable, since most allocators prefer strategic allocations that are greater than 5%. • Market size is perhaps the simplest metric and indicates the significance of the opportunity. • A large investment category is not sufficient, since not every market is accessible or investable. • Availability ensures global investors can participate in a market and that there is sufficient capacity and volume. • Even if the market size is large and availability is high, the investment has to be differentiated compared to everything else in the portfolio. • Otherwise, portfolios may be overexposed to a set of characteristics that are already owned somewhere else. Analysis Summary We define China’s equity market as the sum of all public shares of Chinese companies regardless of where they are listed. The adjusted market capitalization of the Chinese equity market represents 10% of the global equity market. China’s equity market has historically been difficult for investors outside of China to access. Nonetheless, thanks to ambitious inclusion efforts, starting in 2002, Chinese equities have become available to foreign investors. The unique performance characteristics of China’s equity market, which diverge from emerging markets outside of China, warrant its designation as a distinct asset class in diversified portfolios. 6 Data from KraneShares and MSCI as of 30/Sep/2026.
The size of China’s equity market is large enough to be considered its own asset class. China has the world’s second-largest economy and stock market. Data from MSCI as of 31/Dec/2025. See the end of the presentation for definitions.Data from MSCI as of 31/Dec/2025. Due to rounding, numbers may not add up to 100%. Full market capitalization is based on MSCI Investable Market Indexes (IMI). Historic adjusted market capitalizations based on MSCI Standard Indexes. Adjusted market caps reflect free-float or shares that are freely traded in the open market. The free-float adjustment reduces the overall market by about 1/3. China includes Hong Kong, American depositary receipts (ADRs), and Mainland-listed Chinese companies. Market capitalization formula: MSCI China A International IMI + Hong Kong & ADR constituents within the MSCI Emerging Markets Index. Equity Asset Class 2025 Full MARKET CAPITALIZATION USD Billions % Developed Market Equities United States 74,456 51.27 Europe 20,329 14.00 Japan 7,352 5.06 Pacific ex-Japan 3,364 2.32 Other (Israel and Canada) 4,245 2.92 TOTAL DEVELOPED 109,747 75.58 Rest of the World Emerging Markets ex-China 18,244 12.56 China 16,527 11.38 Frontier 693 0.48 TOTAL EM and FM 35,465 24.42 TOTAL 145,212 100.00 0 5 10 15 20 25 30 35 United States China Germany Japan United Kingdom Top 5 Country Weights in the MSCI All Country World Index (GDP Weighted) % Market Size
Opening efforts spanning the past 19 years have made China’s equity market available to outside investors. • In 2002, the Chinese government launched the Qualified Foreign Institutional Investor (QFII) Quota Program, which allowed institutional investors who could demonstrate a limited capacity to repatriate earnings to purchase stocks listed on Mainland exchanges. • From 2014 to 2016 the Stock Connect program was launched, allowing foreign investors to purchase Mainland listed stocks through accounts in Hong Kong without obtaining approval from the Chinese government. • On September 3, 2018, MSCI began including Mainland listed A-shares in their Global Standard Indexes. • 98% of Chinese stocks are listed in Hong Kong, Shenzhen (Mainland), or Shanghai (Mainland) exchanges, while 2% are listed in New York using American Depositary Receipts (ADRs). Data from Bloomberg and MSCI as of 30/Sep/2026. Holdings are subject to change. See page 18 for top 10 holdings. A-Shares (Onshore) Offshore Availability
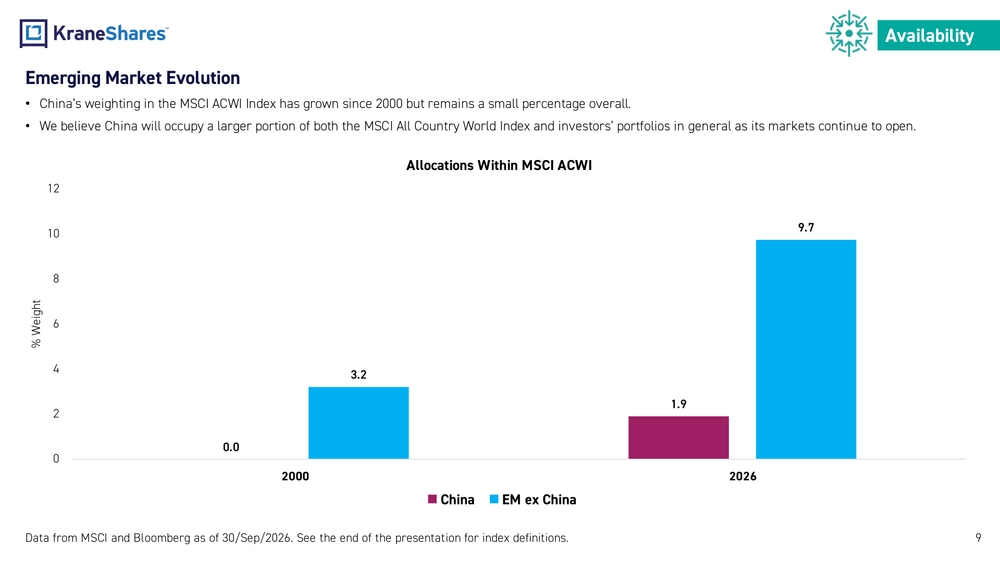
Emerging Market Evolution • China’s weighting in the MSCI ACWI Index has grown since 2000 but remains a small percentage overall. • We believe China will occupy a larger portion of both the MSCI All Country World Index and investors’ portfolios in general a s its markets continue to open. Data from MSCI and Bloomberg as of 30/Sep/2026. See the end of the presentation for index definitions. Availability 9 0.0 1.9 3.2 9.7 0 2 4 6 8 10 12 2000 2026 % Weight Allocations Within MSCI ACWI China EM ex China
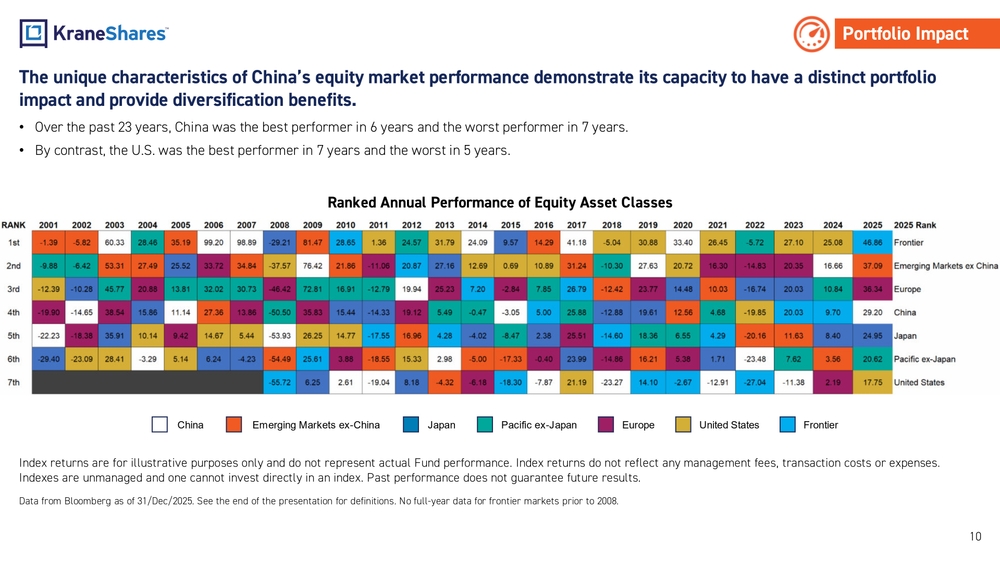
The unique characteristics of China’s equity market performance demonstrate its capacity to have a distinct portfolio impact and provide diversification benefits. • Over the past 23 years, China was the best performer in 6 years and the worst performer in 7 years. • By contrast, the U.S. was the best performer in 7 years and the worst in 5 years. Data from Bloomberg as of 31/Dec/2025. See the end of the presentation for definitions . No full-year data for frontier markets prior to 2008. 10 Ranked Annual Performance of Equity Asset Classes Index returns are for illustrative purposes only and do not represent actual Fund performance. Index returns do not reflect any management fees, transaction costs or expenses. Indexes are unmanaged and one cannot invest directly in an index. Past performance does not guarantee future results. China Emerging Markets ex-China Japan Pacific ex-Japan Europe United States Frontier Portfolio Impact
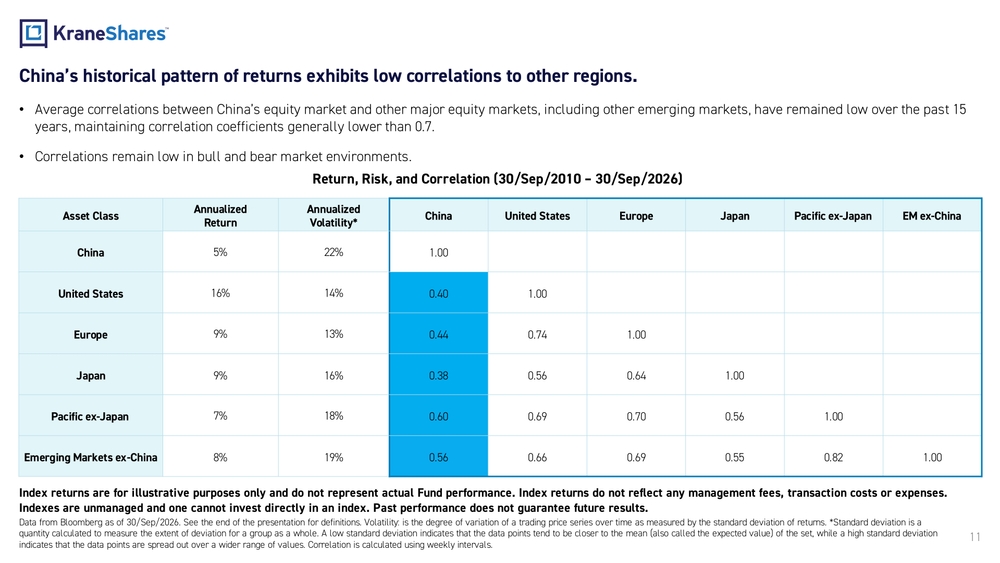
China’s historical pattern of returns exhibits low correlations to other regions. • Average correlations between China’s equity market and other major equity markets, including other emerging markets, have remained low over the past 15 years, maintaining correlation coefficients generally lower than 0.7. • Correlations remain low in bull and bear market environments. Data from Bloomberg as of 30/Sep/2026. See the end of the presentation for definitions. Volatility: is the degree of variation of a trading price series over time as measured by the standard deviation of returns. Standard deviation is a quantity calculated to measure the extent of deviation for a group as a whole. A low standard deviation indicates that the data points tend to be closer to the mean (also called the expected value) of the set, while a high standard deviation indicates that the data points are spread out over a wider range of values. Correlation is calculated using weekly intervals. 11 Index returns are for illustrative purposes only and do not represent actual Fund performance. Index returns do not reflect any management fees, transaction costs or expenses. Indexes are unmanaged and one cannot invest directly in an index. Past performance does not guarantee future results. Return, Risk, and Correlation (30/Sep/2010 – 30/Sep/2026) Asset Class AnnualizedReturn AnnualizedVolatility China United States Europe Japan Pacific ex-Japan EM ex-China China 5% 22% 1.00 United States 16% 14% 0.40 1.00 Europe 9% 13% 0.44 0.74 1.00 Japan 9% 16% 0.38 0.56 0.64 1.00 Pacific ex-Japan 7% 18% 0.60 0.69 0.70 0.56 1.00 Emerging Markets ex-China 8% 19% 0.56 0.66 0.69 0.55 0.82 1.00
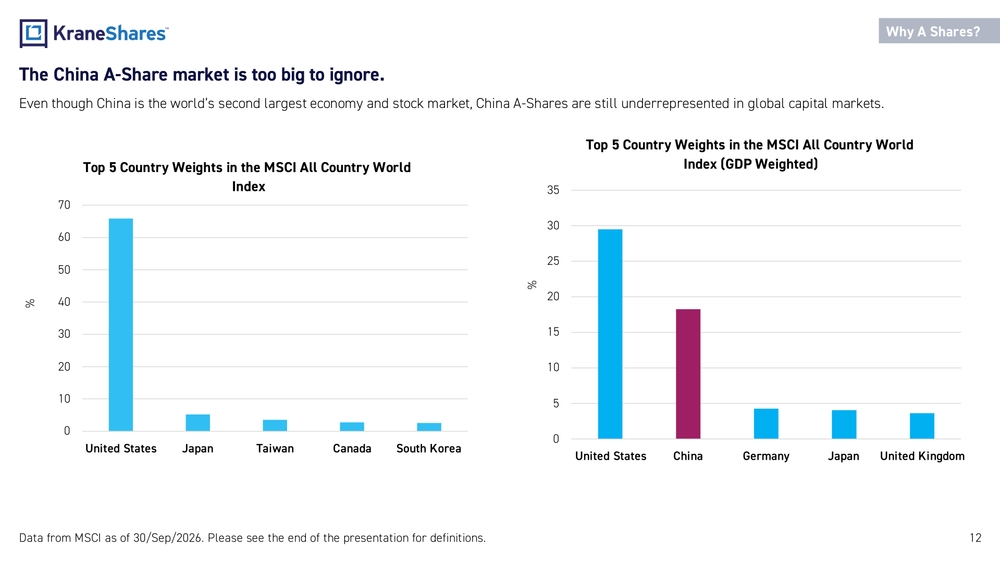
The China A-Share market is too big to ignore. Even though China is the world’s second largest economy and stock market, China A-Shares are still underrepresented in global capital markets. 12Data from MSCI as of 30/Sep/2026. Please see the end of the presentation for definitions. Why A Shares? 0 10 20 30 40 50 60 70 United States Japan Taiwan Canada South Korea Top 5 Country Weights in the MSCI All Country World Index % 0 5 10 15 20 25 30 35 United States China Germany Japan United Kingdom Top 5 Country Weights in the MSCI All Country World Index (GDP Weighted) %
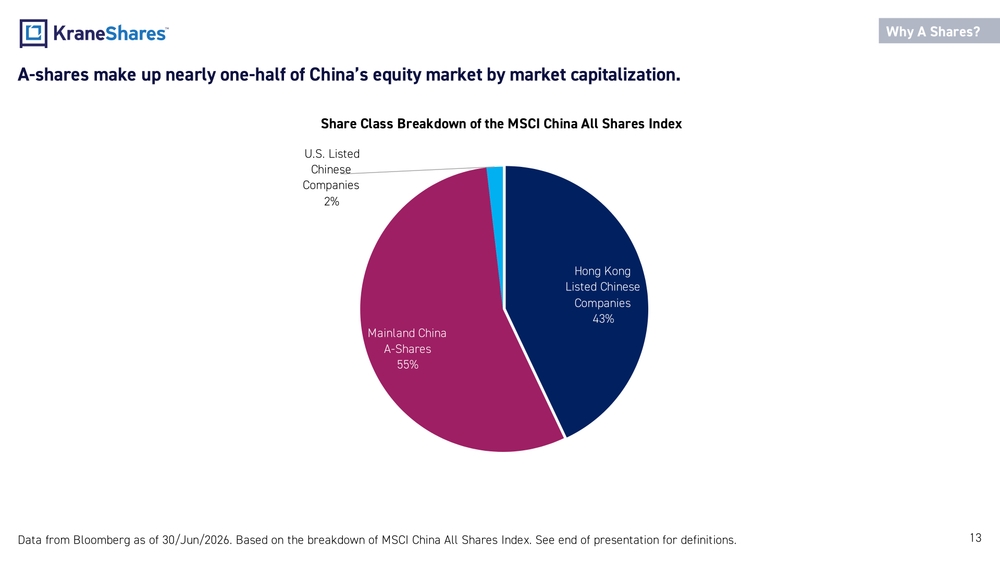
A-shares make up nearly one-half of China’s equity market by market capitalization. Data from Bloomberg as of 30/Jun/2026. Based on the breakdown of MSCI China All Shares Index. See end of presentation for definitions. 13 Why A Shares? Hong Kong Listed Chinese Companies 43% Mainland China A-Shares 55% U.S. Listed Chinese Companies 2% Share Class Breakdown of the MSCI China All Shares Index
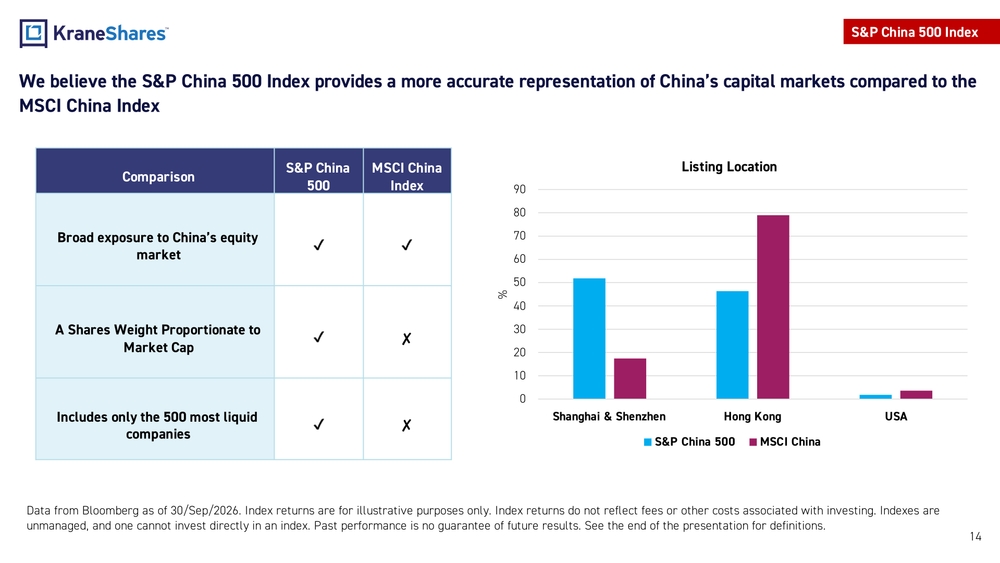
Data from Bloomberg as of 30/Sep/2026. Index returns are for illustrative purposes only. Index returns do not reflect fees or other costs associated with investing. Indexes are unmanaged, and one cannot invest directly in an index. Past performance is no guarantee of future results. See the end of the presentation for definitions. 14 We believe the S&P China 500 Index provides a more accurate representation of China’s capital markets compared to the MSCI China Index Comparison S&P China 500 MSCI China Index Broad exposure to China’s equity market A Shares Weight Proportionate to Market Cap ✘ Includes only the 500 most liquid companies ✘ S&P China 500 Index 0 10 20 30 40 50 60 70 80 90 Shanghai & Shenzhen Hong Kong USA % Listing Location S&P China 500 MSCI China
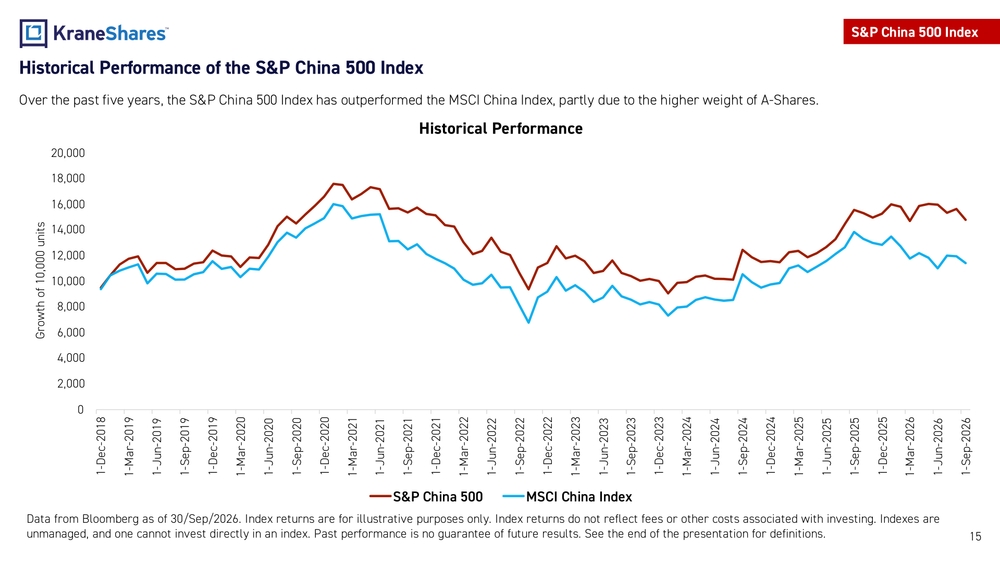
Data from Bloomberg as of 30/Sep/2026. Index returns are for illustrative purposes only. Index returns do not reflect fees or other costs associated with investing. Indexes are unmanaged, and one cannot invest directly in an index. Past performance is no guarantee of future results. See the end of the presentation for definitions. 15 Historical Performance of the S&P China 500 Index Over the past five years, the S&P China 500 Index has outperformed the MSCI China Index, partly due to the higher weight of A-Shares. S&P China 500 Index 0 2,000 4,000 6,000 8,000 10,000 12,000 14,000 16,000 18,000 20,000 1-Dec-2018 1-Mar-2019 1-Jun-2019 1-Sep-2019 1-Dec-2019 1-Mar-2020 1-Jun-2020 1-Sep-2020 1-Dec-2020 1-Mar-2021 1-Jun-2021 1-Sep-2021 1-Dec-2021 1-Mar-2022 1-Jun-2022 1-Sep-2022 1-Dec-2022 1-Mar-2023 1-Jun-2023 1-Sep-2023 1-Dec-2023 1-Mar-2024 1-Jun-2024 1-Sep-2024 1-Dec-2024 1-Mar-2025 1-Jun-2025 1-Sep-2025 1-Dec-2025 1-Mar-2026 1-Jun-2026 1-Sep-2026 Growth of 10,000 units Historical Performance S&P China 500 MSCI China Index
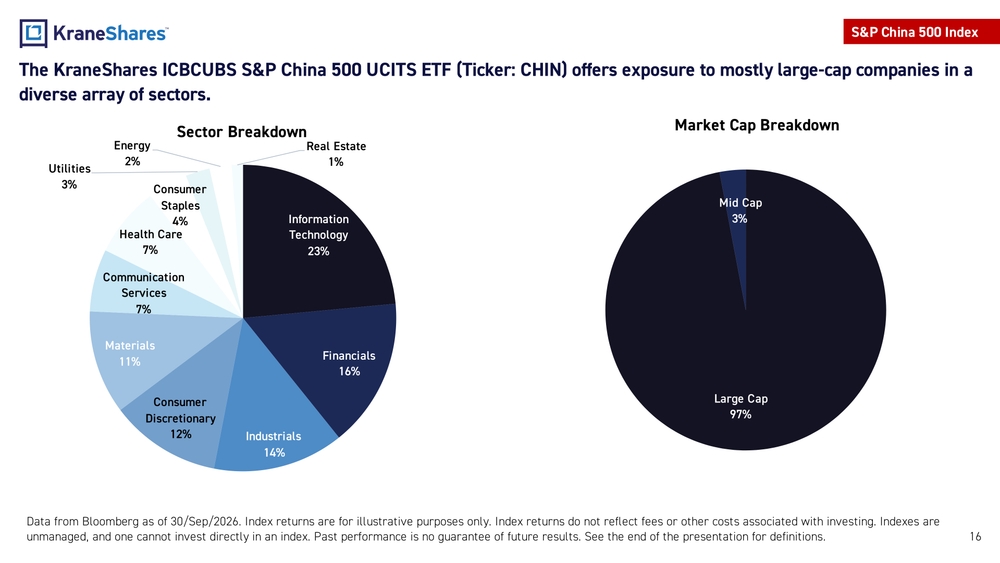
Data from Bloomberg as of 30/Sep/2026. Index returns are for illustrative purposes only. Index returns do not reflect fees or other costs associated with investing. Indexes are unmanaged, and one cannot invest directly in an index. Past performance is no guarantee of future results. See the end of the presentation for definitions. 16 The KraneShares ICBCUBS S&P China 500 UCITS ETF (Ticker: CHIN) offers exposure to mostly large-cap companies in a diverse array of sectors. S&P China 500 Index Large Cap 97% Mid Cap 3% Market Cap Breakdown Information Technology 23% Financials 16% Industrials 14% Consumer Discretionary 12% Materials 11% Communication Services 7% Health Care 7% Consumer Staples 4% Utilities 3% Energy 2% Real Estate 1% Sector Breakdown
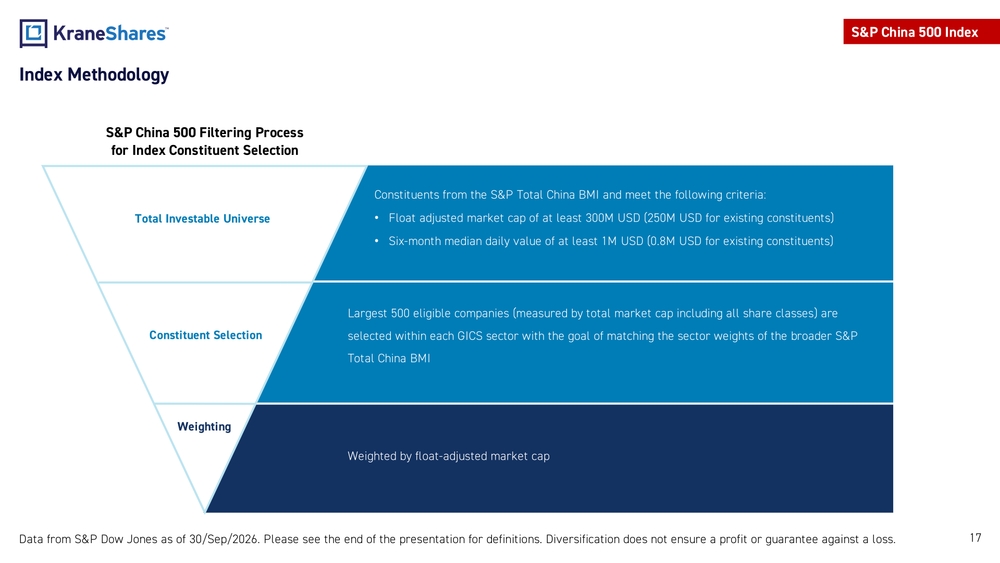
17 Index Methodology A Total Investable Universe Constituent Selection Weighting Constituents from the S&P Total China BMI and meet the following criteria: • Float adjusted market cap of at least 300M USD (250M USD for existing constituents) • Six-month median daily value of at least 1M USD (0.8M USD for existing constituents) Largest 500 eligible companies (measured by total market cap including all share classes) are selected within each GICS sector with the goal of matching the sector weights of the broader S&P Total China BMI Weighted by float-adjusted market cap S&P China 500 Filtering Process for Index Constituent Selection Data from S&P Dow Jones as of 30/Sep/2026. Please see the end of the presentation for definitions. Diversification does not ensure a profit or guarantee against a loss. S&P China 500 Index
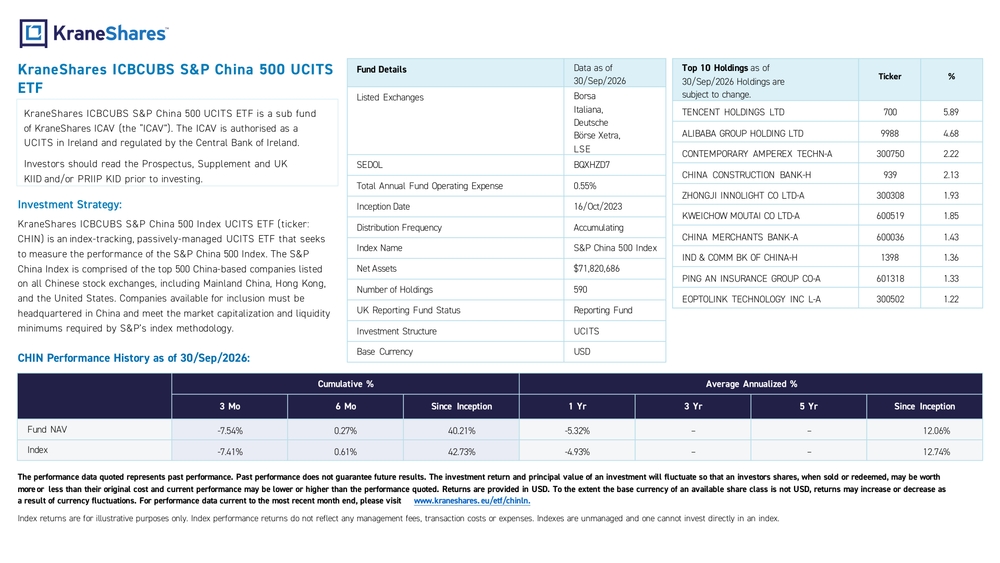
KraneShares ICBCUBS S&P China 500 UCITS ETF KraneShares ICBCUBS S&P China 500 UCITS ETF is a sub fund of KraneShares ICAV (the “ICAV”). The ICAV is authorised as a UCITS in Ireland and regulated by the Central Bank of Ireland. Investors should read the Prospectus, Supplement and UK KIID and/or PRIIP KID prior to investing. Investment Strategy: KraneShares ICBCUBS S&P China 500 Index UCITS ETF (ticker: CHIN) is an index-tracking, passively-managed UCITS ETF that seeks to measure the performance of the S&P China 500 Index. The S&P China Index is comprised of the top 500 China-based companies listed on all Chinese stock exchanges, including Mainland China, Hong Kong, and the United States. Companies available for inclusion must be headquartered in China and meet the market capitalization and liquidity minimums required by S&P’s index methodology. CHIN Performance History as of 30/Sep/2026: Fund Details Data as of 30/Sep/2026 Listed Exchanges Borsa Italiana, Deutsche Börse Xetra, LSE SEDOL BQXHZD7 Total Annual Fund Operating Expense 0.55% Inception Date 16/Oct/2023 Distribution Frequency Accumulating Index Name S&P China 500 Index Net Assets $71,820,686 Number of Holdings 590 UK Reporting Fund Status Reporting Fund Investment Structure UCITS Base Currency USD Top 10 Holdings as of 30/Sep/2026 Holdings are subject to change. Ticker % TENCENT HOLDINGS LTD 700 5.89 ALIBABA GROUP HOLDING LTD 9988 4.68 CONTEMPORARY AMPEREX TECHN-A 300750 2.22 CHINA CONSTRUCTION BANK-H 939 2.13 ZHONGJI INNOLIGHT CO LTD-A 300308 1.93 KWEICHOW MOUTAICO LTD-A 600519 1.85 CHINA MERCHANTS BANK-A 600036 1.43 IND & COMMBK OF CHINA-H 1398 1.36 PING AN INSURANCE GROUP CO-A 601318 1.33 EOPTOLINK TECHNOLOGY INC L-A 300502 1.22 Cumulative % Average Annualized % 3 Mo 6 Mo Since Inception 1 Yr 3 Yr 5 Yr Since Inception Fund NAV -7.54% 0.27% 40.21% -5.32% – – 12.06% Index -7.41% 0.61% 42.73% -4.93% – – 12.74% The performance data quoted represents past performance. Past performance does not guarantee future results. The investment return and principal value of an investment will fluctuate so that an investors shares, when sold or redeemed, may be worth more or less than their original cost and current performance may be lower or higher than the performance quoted. Returns are provided in USD. To the extent the base currency of an available share class is not USD, returns may increase or decrease as a result of currency fluctuations. For performance data current to the most recent month end, please visit www.kraneshares.eu/etf/chinln. Index returns are for illustrative purposes only. Index performance returns do not reflect any management fees, transaction costs or expenses. Indexes are unmanaged and one cannot invest directly in an index.
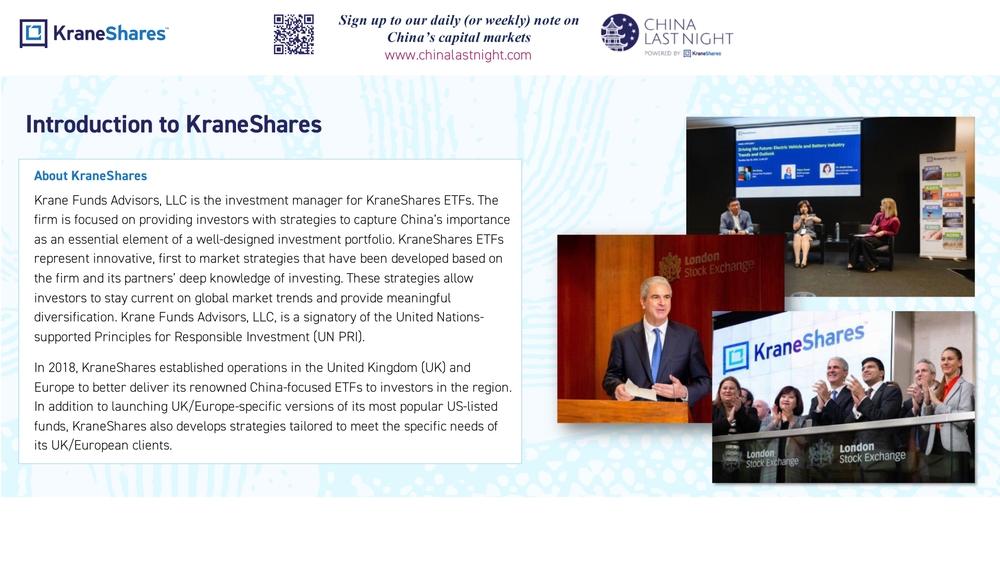
Introduction to KraneShares About KraneShares Krane Funds Advisors, LLC is the investment manager for KraneShares ETFs. The firm is focused on providing investors with strategies to capture China’s importance as an essential element of a well-designed investment portfolio. KraneShares ETFs represent innovative, first to market strategies that have been developed based on the firm and its partners’ deep knowledge of investing. These strategies allow investors to stay current on global market trends and provide meaningful diversification. Krane Funds Advisors, LLC, is a signatory of the United Nations- supported Principles for Responsible Investment (UN PRI). In 2018, KraneShares established operations in the United Kingdom (UK) and Europe to better deliver its renowned China-focused ETFs to investors in the region. In addition to launching UK/Europe-specific versions of its most popular US-listed funds, KraneShares also develops strategies tailored to meet the specific needs of its UK/European clients. Sign up to our daily (or weekly) note on China’s capital markets www.chinalastnight.com
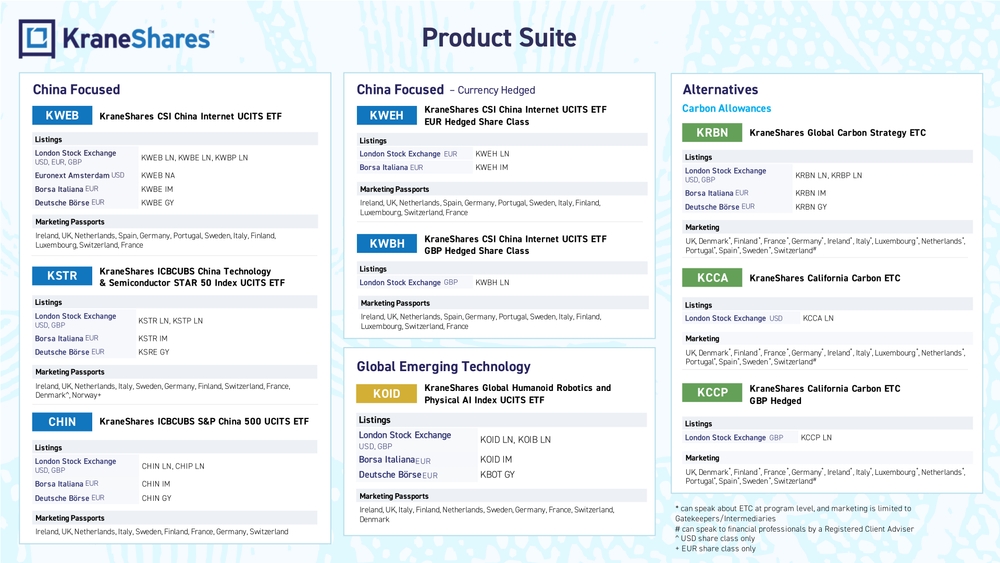
China Focused Alternatives Global Emerging Technology Carbon Allowances Product Suite KraneShares Global Carbon Strategy ETCKRBN KCCA KraneShares California Carbon ETC KCCP KraneShares California Carbon ETCGBP Hedged China Focused – Currency Hedged Listings London Stock Exchange USD, EUR, GBP KWEB LN, KWBE LN, KWBP LN Euronext Amsterdam USD KWEB NA Borsa Italiana EUR KWBE IM Deutsche Börse EUR KWBE GY Marketing Passports Ireland, UK, Netherlands, Spain, Germany, Portugal, Sweden, Italy, Finland, Luxembourg, Switzerland, France Listings London Stock Exchange USD, GBP CHIN LN, CHIP LN Borsa Italiana EUR CHIN IM Deutsche Börse EUR CHIN GY Marketing Passports Ireland, UK, Netherlands, Italy, Sweden, Finland, France, Germany, Switzerland Listings London Stock Exchange USD, GBP KSTR LN, KSTP LN Borsa Italiana EUR KSTR IM Deutsche Börse EUR KSRE GY Marketing Passports Ireland, UK, Netherlands, Italy, Sweden, Germany, Finland, Switzerland, France, Denmark^, Norway+ KWEH KraneShares CSI China Internet UCITS ETFEUR Hedged Share Class Listings London Stock Exchange EUR KWEH LN Borsa Italiana EUR KWEH IM KWBH KraneShares CSI China Internet UCITS ETFGBP Hedged Share Class Listings London Stock Exchange GBP KWBH LN KOID KraneShares Global Humanoid Robotics andPhysical AI Index UCITS ETF Listings London Stock Exchange USD, GBP KOID LN, KOIB LN Borsa Italiana EUR KOID IM Deutsche Börse EUR KBOT GY Marketing Passports Ireland, UK, Italy, Finland, Netherlands, Sweden, Germany, France, Switzerland, Denmark Listings London Stock Exchange USD, GBP KRBN LN, KRBP LN Borsa Italiana EUR KRBN IM Deutsche Börse EUR KRBN GY Marketing UK, Denmark*, Finland*, France*, Germany*, Ireland*, Italy*, Luxembourg*, Netherlands*, Portugal*, Spain*, Sweden*, Switzerland# Listings London Stock Exchange USD KCCA LN Marketing UK, Denmark*, Finland*, France*, Germany*, Ireland*, Italy*, Luxembourg*, Netherlands*, Portugal*, Spain*, Sweden*, Switzerland# Listings London Stock Exchange GBP KCCP LN Marketing UK, Denmark*, Finland*, France*, Germany*, Ireland*, Italy*, Luxembourg*, Netherlands*, Portugal*, Spain*, Sweden*, Switzerland# KSTR KraneShares ICBCUBS China Technology & Semiconductor STAR 50 Index UCITS ETF KraneShares ICBCUBS S&P China 500 UCITS ETFCHIN KWEB KraneShares CSI China Internet UCITS ETF Marketing Passports Ireland, UK, Netherlands, Spain, Germany, Portugal, Sweden, Italy, Finland, Luxembourg, Switzerland, France Marketing Passports Ireland, UK, Netherlands, Spain, Germany, Portugal, Sweden, Italy, Finland, Luxembourg, Switzerland, France
- can speak about ETC at program level, and marketing is limited to Gatekeepers/Intermediaries
can speak to financial professionals by a Registered Client Adviser
^ USD share class only
- EUR share class only
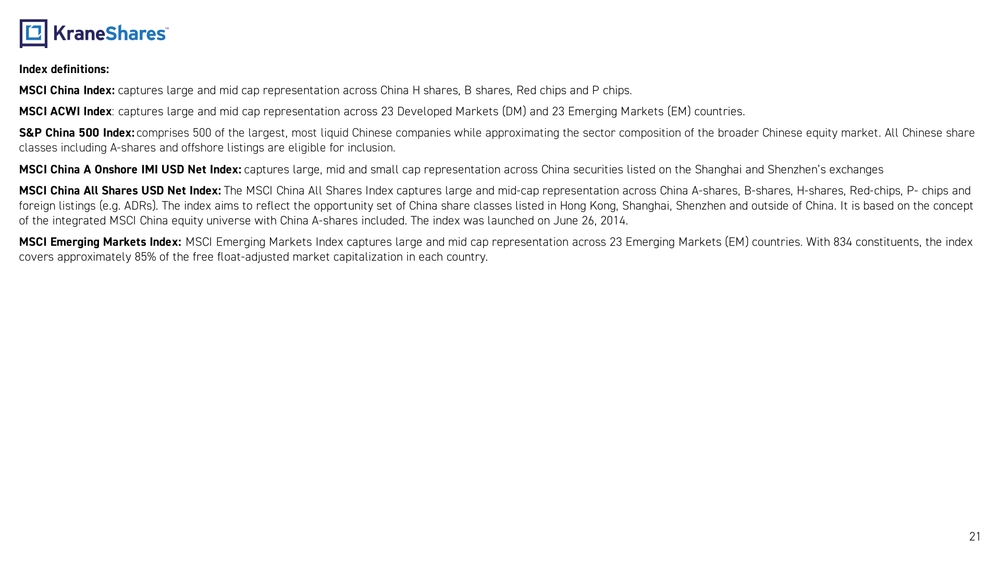
21 Index definitions: MSCI China Index: captures large and mid cap representation across China H shares, B shares, Red chips and P chips. MSCI ACWI Index: captures large and mid cap representation across 23 Developed Markets (DM) and 23 Emerging Markets (EM) countries. S&P China 500 Index: comprises 500 of the largest, most liquid Chinese companies while approximating the sector composition of the broader Chinese equity market. All Chinese share classes including A-shares and offshore listings are eligible for inclusion. MSCI China A Onshore IMI USD Net Index: captures large, mid and small cap representation across China securities listed on the Shanghai and Shenzhen’s exchanges MSCI China All Shares USD Net Index: The MSCI China All Shares Index captures large and mid-cap representation across China A‐shares, B‐shares, H‐shares, Red‐chips, P‐ chips and foreign listings (e.g. ADRs). The index aims to reflect the opportunity set of China share classes listed in Hong Kong, Shanghai, Shenzhen and outside of China. It is based on the concept of the integrated MSCI China equity universe with China A-shares included. The index was launched on June 26, 2014. MSCI Emerging Markets Index: MSCI Emerging Markets Index captures large and mid cap representation across 23 Emerging Markets (EM) countries. With 834 constituents, the index covers approximately 85% of the free float-adjusted market capitalization in each country.
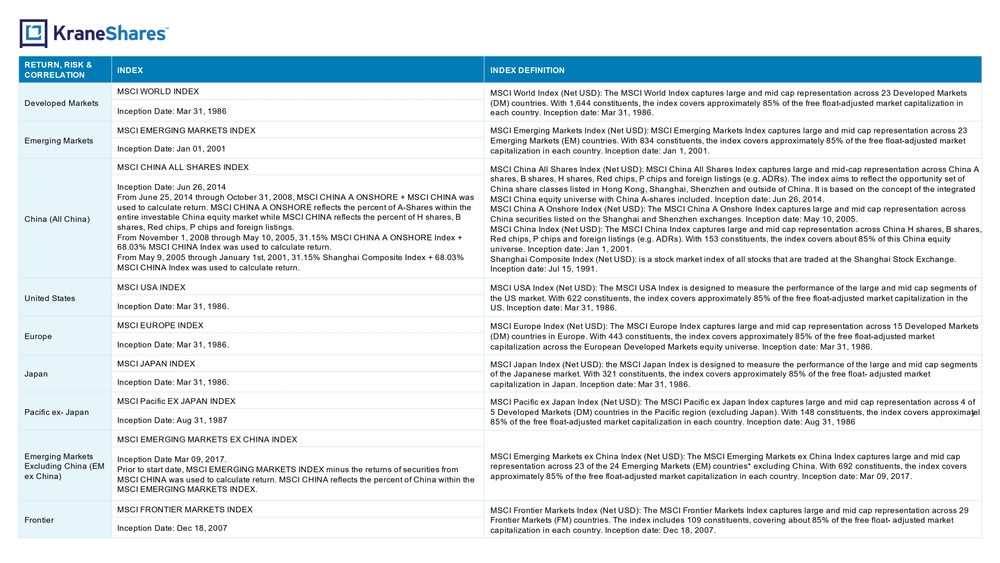
RETURN, RISK & CORRELATION INDEX INDEX DEFINITION Developed Markets MSCI WORLD INDEX MSCI World Index (Net USD): The MSCI World Index captures large and mid cap representation across 23 Developed Markets (DM) countries. With 1,644 constituents, the index covers approximately 85% of the free float-adjusted market capitalization in each country. Inception date: Mar 31, 1986. Inception Date: Mar 31, 1986 Emerging Markets MSCI EMERGING MARKETS INDEX MSCI Emerging Markets Index (Net USD): MSCI Emerging Markets Index captures large and mid cap representation across 23 Emerging Markets (EM) countries. With 834 constituents, the index covers approximately 85% of the free float-adjusted market capitalization in each country. Inception date: Jan 1, 2001. Inception Date: Jan 01, 2001 China (All China) MSCI CHINA ALL SHARES INDEX MSCI China All Shares Index (Net USD): MSCI China All Shares Index captures large and mid-cap representation across China A shares, B shares, H shares, Red chips, P chips and foreign listings (e.g. ADRs). The index aims to reflect the opportunity set of China share classes listed in Hong Kong, Shanghai, Shenzhen and outside of China. It is based on the concept of the integrate d MSCI China equity universe with China A-shares included. Inception date: Jun 26, 2014. MSCI China A Onshore Index (Net USD): The MSCI China A Onshore Index captures large and mid cap representation across China securities listed on the Shanghai and Shenzhen exchanges. Inception date: May 10, 2005. MSCI China Index (Net USD): The MSCI China Index captures large and mid cap representation across China H shares, B shares, Red chips, P chips and foreign listings (e.g. ADRs). With 153 constituents, the index covers about 85% of this China equity universe. Inception date: Jan 1, 2001. Shanghai Composite Index (Net USD): is a stock market index of all stocks that are traded at the Shanghai Stock Exchange. Inception date: Jul 15, 1991. Inception Date: Jun 26, 2014 From June 25, 2014 through October 31, 2008, MSCI CHINA A ONSHORE + MSCI CHINA was used to calculate return. MSCI CHINA A ONSHORE reflects the percent of A-Shares within the entire investable China equity market while MSCI CHINA reflects the percent of H shares, B shares, Red chips, P chips and foreign listings. From November 1, 2008 through May 10, 2005, 31.15% MSCI CHINA A ONSHORE Index + 68.03% MSCI CHINA Index was used to calculate return. From May 9, 2005 through January 1st, 2001, 31.15% Shanghai Composite Index + 68.03% MSCI CHINA Index was used to calculate return. United States MSCI USA INDEX MSCI USA Index (Net USD): The MSCI USA Index is designed to measure the performance of the large and mid cap segments of the US market. With 622 constituents, the index covers approximately 85% of the free float-adjusted market capitalization in the US. Inception date: Mar 31, 1986.Inception Date: Mar 31, 1986. Europe MSCI EUROPE INDEX MSCI Europe Index (Net USD): The MSCI Europe Index captures large and mid cap representation across 15 Developed Markets (DM) countries in Europe. With 443 constituents, the index covers approximately 85% of the free float-adjusted market capitalization across the European Developed Markets equity universe. Inception date: Mar 31, 1986. Inception Date: Mar 31, 1986. Japan MSCI JAPAN INDEX MSCI Japan Index (Net USD): the MSCI Japan Index is designed to measure the performance of the large and mid cap segments of the Japanese market. With 321 constituents, the index covers approximately 85% of the free float- adjusted market capitalization in Japan. Inception date: Mar 31, 1986.Inception Date: Mar 31, 1986. Pacific ex- Japan MSCI Pacific EX JAPAN INDEX MSCI Pacific ex Japan Index (Net USD): The MSCI Pacific ex Japan Index captures large and mid cap representation across 4 of 5 Developed Markets (DM) countries in the Pacific region (excluding Japan). With 148 constituents, the index covers approximately 85% of the free float-adjusted market capitalization in each country. Inception date: Aug 31, 1986Inception Date: Aug 31, 1987 Emerging Markets Excluding China (EM ex China) MSCI EMERGING MARKETS EX CHINA INDEX MSCI Emerging Markets ex China Index (Net USD): The MSCI Emerging Markets ex China Index captures large and mid cap representation across 23 of the 24 Emerging Markets (EM) countries* excluding China. With 692 constituents, the index covers approximately 85% of the free float-adjusted market capitalization in each country. Inception date: Mar 09, 2017. Inception Date Mar 09, 2017. Prior to start date, MSCI EMERGING MARKETS INDEX minus the returns of securities from MSCI CHINA was used to calculate return. MSCI CHINA reflects the percent of China within the MSCI EMERGING MARKETS INDEX. Frontier MSCI FRONTIER MARKETS INDEX MSCI Frontier Markets Index (Net USD): The MSCI Frontier Markets Index captures large and mid cap representation across 29 Frontier Markets (FM) countries. The index includes 109 constituents, covering about 85% of the free float- adjusted market capitalization in each country. Inception date: Dec 18, 2007.Inception Date: Dec 18, 2007
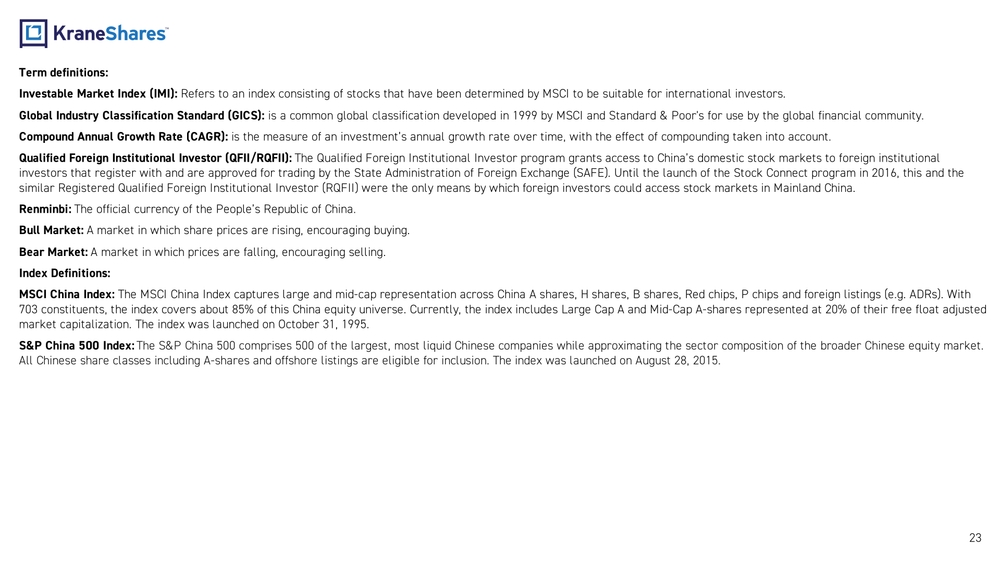
23 Term definitions: Investable Market Index (IMI): Refers to an index consisting of stocks that have been determined by MSCI to be suitable for international investors. Global Industry Classification Standard (GICS): is a common global classification developed in 1999 by MSCI and Standard & Poor's for use by the global financial community. Compound Annual Growth Rate (CAGR): is the measure of an investment’s annual growth rate over time, with the effect of compounding taken into account. Qualified Foreign Institutional Investor (QFII/RQFII):The Qualified Foreign Institutional Investor program grants access to China’s domestic stock markets to foreign institutional investors that register with and are approved for trading by the State Administration of Foreign Exchange (SAFE). Until the launch of the Stock Connect program in 2016, this and the similar Registered Qualified Foreign Institutional Investor (RQFII) were the only means by which foreign investors could access stock markets in Mainland China. Renminbi: The official currency of the People’s Republic of China. Bull Market: A market in which share prices are rising, encouraging buying. Bear Market: A market in which prices are falling, encouraging selling. Index Definitions: MSCI China Index: The MSCI China Index captures large and mid-cap representation across China A shares, H shares, B shares, Red chips, P chips and foreign listings (e.g. ADRs). With 703 constituents, the index covers about 85% of this China equity universe. Currently, the index includes Large Cap A and Mid-Cap A-shares represented at 20% of their free float adjusted market capitalization. The index was launched on October 31, 1995. S&P China 500 Index: The S&P China 500 comprises 500 of the largest, most liquid Chinese companies while approximating the sector composition of the broader Chinese equity market. All Chinese share classes including A-shares and offshore listings are eligible for inclusion. The index was launched on August 28, 2015.
24 Important Notes Carefully consider the Funds’ investment objectives, risk factors, charges and expenses before investing. This and additional information can be found in the Funds‘ full and summary prospectus, which may be obtained by visiting www.kraneshares.eu. Read the prospectus carefully before investing. Risk Disclosures The views and opinions expressed in this material are those of authors of the Krane Fund Advisors. These opinions have been given in faith, but are subject to change without notice. It is the responsibility of the investor to evaluate the accuracy, completeness and usefulness of any opinions, advice or other information provided. Instead, investors must buy and sell UCITS shares in the secondary market with the assistance of a stockbroker. UCITS ETF’s units/shares purchased on the secondary market cannot usually be sold directly back t the UCITS ETF. Investors must buy and sell units/shares on a seconfary market with the assistance if an intermediary (e.g. a stockbroker) and may incur fees for doing so. In addition, investors may pay more than the current net asset value when buying units/shares and may receive less than the current net asset value when selling them. UCITS shares are not individually redeemable with the issuing fund other than in large Creation Unit aggregations. In doing so, the investor may incur brokerage commissions and may pay more than net asset value (NAV) when buying and receive less than net asset value (NAV) when selling. The Net Asset Value per share is calculated in accordance with the “Determination of Net Asset Value” section of the prospectus, using the official closing price published by the relevant exchange. Shares are bought and sold at market price which may or may not be consistent with NAV. Investing involves risk, including possible loss of principal. There can be no assurance that a Fund will achieve its stated objectives. The Funds are subject to political, social or economic instability within China which may cause decline in value. Fluctuations in currency of foreign countries may have an adverse effect to domestic currency values. Emerging markets involve heightened risk related to the same factors as well as increase volatility and lower trading volume. The ability of the Fund to achieve its respective investment objectives is dependent, in part, on the continuous availability of A Shares and the ability to obtain, if necessary, additional A Shares quota. If the Fund is unable to obtain sufficient exposure to limited availability of A Share quota, the Fund could seek exposure to the component securities of the Underlying Index by investment in other types of securities. The Fund is subject to political, social or economic instability within China which may cause decline in value. Emerging markets involve heightened risk related to the same factors as well as increase volatility and lower trading volume. Fluctuations in currency of foreign countries may have an adverse effect to domestic currency values. The Fund may invest in Initial Public Offerings (IPOs). Securities issued in IPOs have no trading history, and information about the companies may be available for very limited periods. In addition, the prices of securities sold in IPOs may be highly volatile. In addition, as the Fund increases in size, the impact of IPOs on the Fund’s performance will generally decrease. Narrowly focused investments typically exhibit higher volatility. The Fund’s assets are expected to be concentrated in a sector, industry, market, or group of concentrations to the extent that the Underlying Index has such concentrations. The securities or futures in that concentration could react similarly to market developments. Thus, the Fund is subject to loss due to adverse occurrences that affect that concentration. In addition to the normal risks associated with investing, investments in smaller companies typically exhibit higher volatility. This material is for information only and does not constitute an offer or recommendation to buy or sell any investment, or subscribe to any investment management or advisory service. It is not, under any circumstances, intended for distribution to the general public. You are accessing information which constitutes a financial promotion under section 21 of the Financial Services and Markets Act 2000 ("FSMA"). In relation to the United Kingdom, this information is only directed at, and may only be distributed to, persons who are “Investment Professionals” (being persons having professional experience in matters relating to investments) within the meaning of article 19(5) of the FSMA (Financial Promotion) Order 2005 (the “Financial Promotion Order ”), persons to whom any of paragraphs (2)(a) to (d) of article 49 (high net worth companies, unincorporated associations etc.) of the financial promotion order apply, or persons to whom distribution may otherwise lawfully be made.
25 Risk Disclosures Continued: Any investment, and investment activity or controlled activity, to which this information relates is available only to such persons and will be engaged in only with such persons. Persons that do not have professional experience should not rely or act upon this information unless they are persons to whom any of paragraphs (2)(a) to (d) of article 49 apply to whom distribution of this information may otherwise lawfully be made. In Switzerland, the Fund has appointed as Swiss Representative Waystone Fund Services (Switzerland) SA, Av. Villamont 17, 1005 Lausanne, Switzerland, Tel: +41 21 311 17 77, email: switzerland@waystone.com. The Fund’s paying agent is Helvetische Bank AG. In respect of the Shares distributed in or from Switzerland, the place of performance and jurisdiction is Lausanne (Switzerland). Although the information provided in this document has been obtained from sources which Krane Funds Advisors, LLC believes to be reliable, it does not guarantee accuracy of such information and such information may be incomplete or condensed. Krane Fund Advisors, LLC is appointed to act as investment manager in accordance with the requirements of the Central Bank. The Management Company may decide to terminate the agreements made for the marketing of the Fund in accordance with Article 93a of Directive 2009/65/EC. This and additional information, including historical and the most recent month-end performance, can be found in the Fund Literature (Prospectus, Supplement, KIID, PRIIP), please visit www.waystone.com, or www.kraneshares.eu. The Fund operates a full portfolio transparency policy. The Fund's complete portfolio holdings are published daily and are available on the Fund's webpage at https://www.kraneshares.eu/kstrln. The Fund's indicative net asset value (iNAV) can be obtained during trading hours at https://www.londonstockexchange.com/stock/CHIN/kraneshares-icav/company- page R_EU_KS